Introduction
Renewal Maruti insurance is one of those tasks that most car owners put off until the last week, and sometimes the last day. Maruti Suzuki is India’s most popular car brand, with models like the Alto, Swift, Baleno, Wagon R, Brezza, Ertiga and Dzire on millions of roads. If you own one, your car insurance policy needs to be renewed every year to keep you legally covered and financially protected.
In this guide, you will learn exactly how the renewal Maruti insurance process works, what documents you need, how to renew online in minutes, how to save money on your premium, and what happens if you miss the deadline. Whether you drive a ten-year-old Alto or a brand-new Grand Vitara, this guide will help you renew with confidence.
Why Renewal of Maruti Insurance Is Important
Under the Motor Vehicles Act, 1988, every vehicle running on Indian roads must have at least a valid third-party insurance policy. Driving without one can attract heavy fines and even imprisonment, and penalties increase for repeat offences. Beyond the legal angle, timely renewal Maruti insurance protects you in several ways:
- Financial protection: Covers repair costs after accidents, theft, fire, floods and other damage.
- Third-party liability cover: Protects you from legal and financial liability if your car injures someone or damages their property.
- Personal accident cover: The owner-driver personal accident cover is mandatory and is included in most policies.
- Continuity of benefits: A timely renewal keeps your No Claim Bonus (NCB) and add-on benefits intact.
Types of Maruti Suzuki Car Insurance Policies You Can Renew
Before you start the renewal, decide which type of policy suits your car.
1. Third-Party Liability Policy
This is the minimum legal requirement. It covers damage or injury caused to another person, vehicle or property, but it does not cover damage to your own Maruti car. The premium is fixed by IRDAI, so it is the same across insurers.
2. Comprehensive Car Insurance
A comprehensive policy covers third-party liability plus damage to your own car from accidents, theft, fire, natural calamities and man-made disasters. For most Maruti owners, especially those with cars under ten years old, this is the better choice.
3. Standalone Own-Damage Policy
If you already hold a long-term third-party policy, you can buy a standalone own-damage cover and renew it every year.
When Should You Do Your Renewal Maruti Insurance?
The best time to renew is 15 to 30 days before your policy expiry date. Renewing early gives you time to compare plans, choose add-ons and avoid last-minute stress. Most insurers send renewal reminders by SMS, email and WhatsApp, so keep your contact details updated.
If you renew before expiry, your new policy starts right after the old one ends, and your NCB is fully protected.
Documents Required for Maruti Insurance Renewal
The good news is that renewal needs very little paperwork. Keep these handy:
- Previous policy number or expired policy copy
- Registration Certificate (RC) of your Maruti car
- Valid Pollution Under Control (PUC) certificate
- Registration number, make, model and variant details
- Driving licence of the owner-driver
- KYC details (Aadhaar or PAN, as required by the insurer)
How to Renew Maruti Insurance Online: Step-by-Step
Online renewal is quick, paperless and usually cheaper than offline renewal. Here is how to do it.
Step 1: Visit the insurer’s website or a trusted insurance platform
Go to your current insurer’s website or app, or use a reliable insurance comparison platform. Search for the car insurance renewal section.
Step 2: Enter your car details
Enter your Maruti registration number or previous policy number. The system will fetch your car details automatically.
Step 3: Verify policy and vehicle information
Check the make, model, variant, fuel type, registration year and city. Any error here can affect your premium or claim later.
Step 4: Choose your policy type and IDV
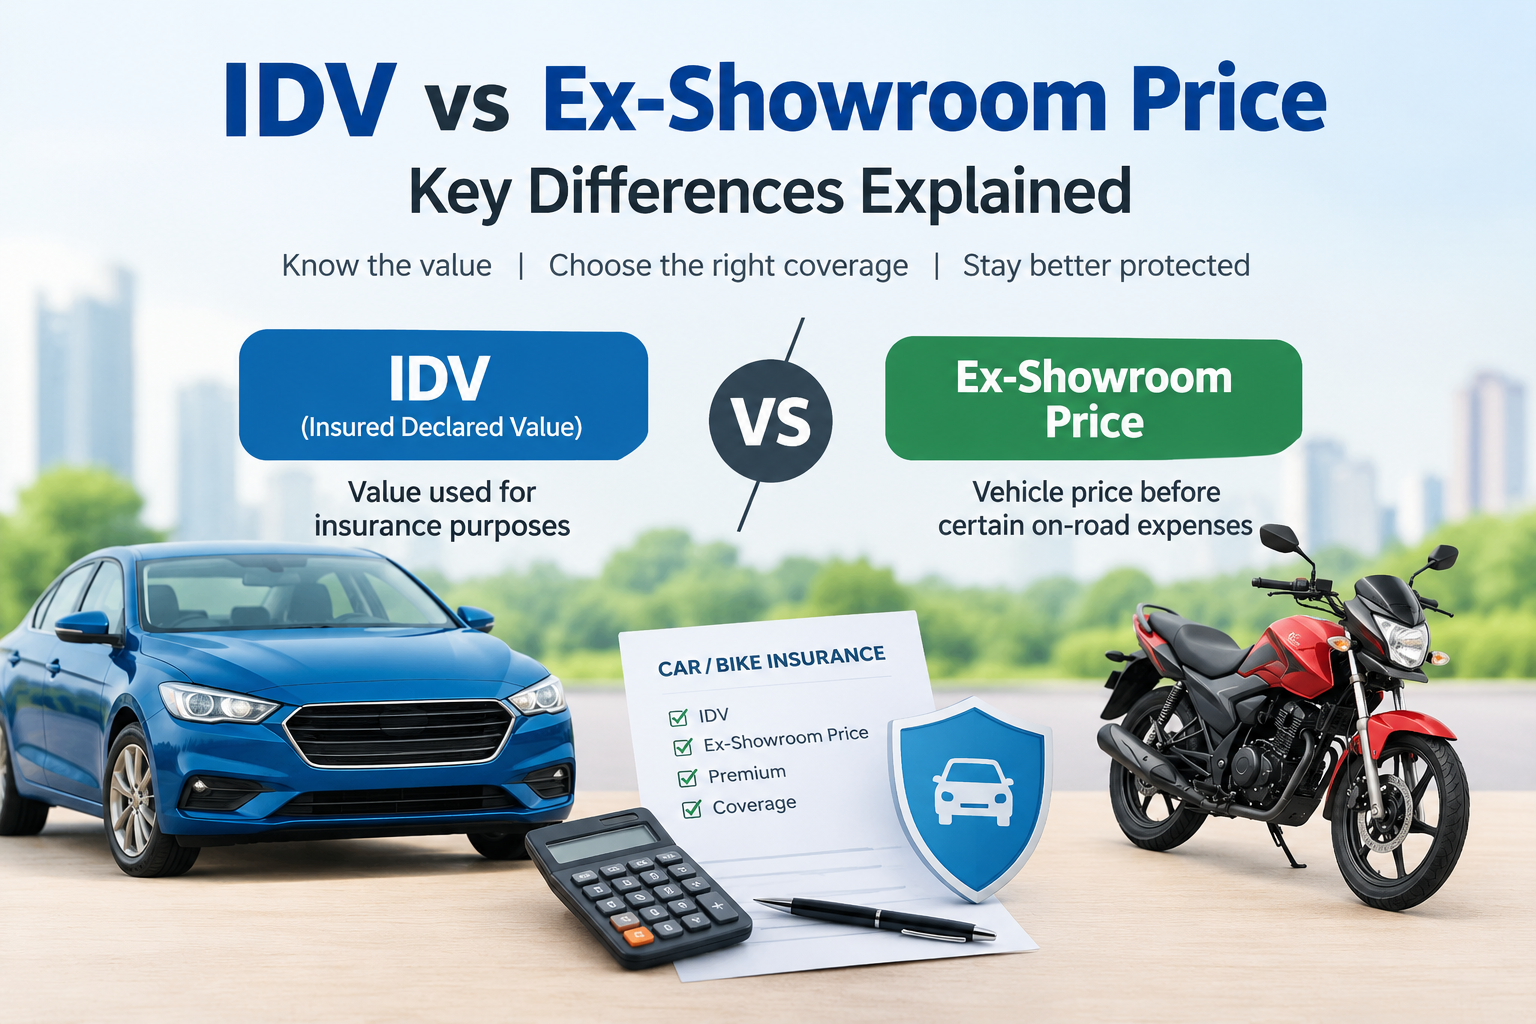
Select comprehensive, third-party or own-damage cover. Review the Insured Declared Value (IDV), which is the market value of your car and the maximum amount you can get in case of total loss or theft. Do not lower the IDV just to reduce the premium, because it hurts you at claim time.
Step 5: Select useful add-ons
Pick add-ons based on your car’s age and usage (details in the next section).
Step 6: Compare quotes and pay
Compare the renewal Maruti insurance premium across insurers, then pay securely using UPI, net banking, debit or credit card.
Step 7: Download your policy
Your policy document is emailed instantly. Save a digital copy on your phone and in DigiLocker.
Best Add-Ons to Consider While Renewing Maruti Insurance
Add-ons increase your premium slightly but can save you thousands at claim time.
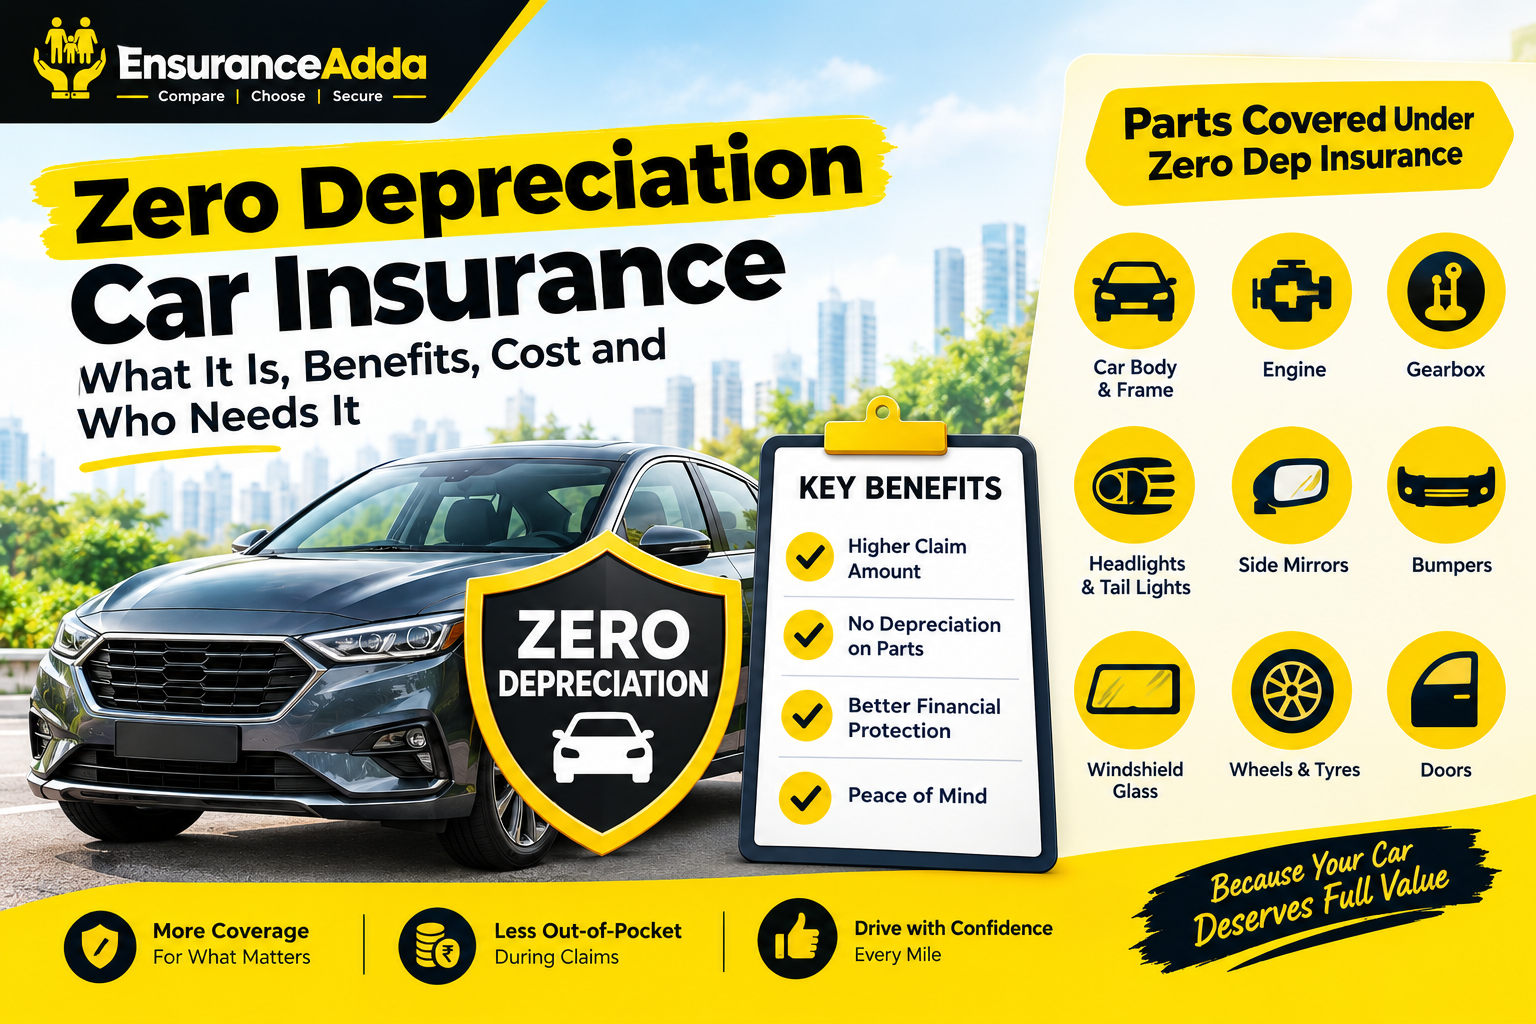
- Zero Depreciation Cover: Pays the full cost of replaced parts without depreciation deductions. Ideal for cars under five years old.
- Engine Protection Cover: Covers engine damage from water ingression or oil leakage, which is useful in flood-prone areas.
- Roadside Assistance: Helps with breakdowns, flat tyres, towing and fuel delivery.
- Return to Invoice: Pays the full invoice value if your car is stolen or declared a total loss.
- Consumables Cover: Covers nuts, bolts, engine oil, coolant and similar items that are normally excluded.
- NCB Protection: Lets you keep your No Claim Bonus even after making one claim.
Understanding No Claim Bonus (NCB) in Maruti Insurance Renewal
No Claim Bonus is a discount on your own-damage premium for every claim-free year. It starts at 20% after the first claim-free year and goes up to 50% after five consecutive claim-free years.
Two important points:
- NCB belongs to you, not to the car or the insurer. You can carry it forward if you switch insurers.
- NCB is generally lost if the policy lapses for a long gap after expiry, so timely renewal Maruti insurance matters.
How Is the Maruti Insurance Renewal Premium Calculated?
Several factors decide your renewal premium:
- Car model and variant: A Maruti Swift VXi will have a different premium than an Alto K10.
- Age of the car: Older cars have a lower IDV and usually a lower premium.
- Engine capacity (cc): Third-party premium is set by cubic capacity bands.
- IDV: A higher IDV means a higher premium.
- Add-ons: Each add-on adds to the cost.
- NCB: Your accumulated discount lowers the own-damage premium.
- Location: Cities with higher theft and accident rates may have higher premiums.
- Claim history: Frequent claims can reduce discounts.
Tips to Save Money on Renewal Maruti Insurance
- Compare before you renew. Do not auto-renew blindly. Comparing three to four quotes can reveal meaningful savings.
- Protect your NCB. Avoid small claims for minor dents and scratches.
- Choose a sensible voluntary deductible. A higher deductible can lower the premium, but make sure you can afford it during a claim.
- Buy only the add-ons you need. A ten-year-old car may not need zero depreciation or return to invoice.
- Install anti-theft devices. Approved devices can earn a discount with some insurers.
- Renew online. Digital policies often come with lower costs than offline ones.
Maruti Insurance Renewal After Expiry: What Happens?
If you miss the deadline, things get more complicated:
- Shortly after expiry: You may still renew, but the insurer will likely require a vehicle inspection, and there is a gap in cover. Any accident during the gap is not covered.
- After a long lapse: You can lose your No Claim Bonus entirely.
- Very long lapse: The insurer may treat your renewal like a fresh policy, with inspection and possibly a higher premium.
This is why setting a reminder 30 days before expiry is a simple habit worth building.
Maruti Insurance Renewal: Online vs Dealer
Many Maruti owners renew through the dealership because it feels convenient. But it is wise to compare.
| Factor | Online Renewal | Dealer Renewal |
|---|---|---|
| Time taken | 5 to 10 minutes | Visit and wait |
| Quote comparison | Easy, multiple insurers | Limited options |
| Premium | Often lower | Can be higher |
| Paperwork | Minimal | More documents |
| Add-on choice | Flexible | May be bundled |
Both routes are valid. What matters is that you review the IDV, add-ons and exclusions before paying.
Common Mistakes to Avoid During Maruti Insurance Renewal
- Letting the policy lapse, even for a day
- Under-declaring IDV to cut the premium
- Not updating the policy after a change in address, ownership or modifications
- Ignoring add-ons that suit your usage
- Not disclosing previous claims honestly
- Skipping the policy wording and exclusions
Frequently Asked Questions (FAQs)
1. Can I renew my Maruti insurance online?
Yes. You can complete renewal Maruti insurance online in under ten minutes using your registration number or previous policy number.
2. Is inspection required for Maruti insurance renewal?
If you renew before the policy expires, inspection is usually not needed. If the policy has lapsed, the insurer may ask for an inspection.
3. Can I switch insurers while renewing?
Yes. You can switch to a different insurer at renewal and carry forward your NCB by showing your previous policy details.
4. Is there a grace period for renewal?
Car insurance has no official grace period. Any day without cover is a day you are uninsured, and a long gap can cost you your NCB.
5. What happens if my Maruti insurance expires?
Your car is uninsured from the expiry date. You cannot claim for damage, and you may face legal penalties if you drive without valid third-party cover.
6. Does the renewal premium increase every year?
Not always. The premium depends on IDV depreciation, NCB, claim history and insurer pricing. A good claim history often reduces your premium.
Conclusion
Renewal Maruti insurance does not have to be complicated or expensive. By renewing 15 to 30 days before expiry, comparing quotes, choosing the right IDV and add-ons, and protecting your No Claim Bonus, you can keep your Maruti Suzuki fully covered and save money in the process. Set a calendar reminder today, keep your documents ready, and complete your renewal online in just a few minutes.