Have you ever filed a car insurance claim and received far less than the repair bill? The reason is usually depreciation. Zero depreciation car insurance is designed to fix exactly that problem. In this guide, you’ll learn what it is, what it covers, what it costs, and whether it’s worth buying for your car.
What Is Zero Depreciation Car Insurance?
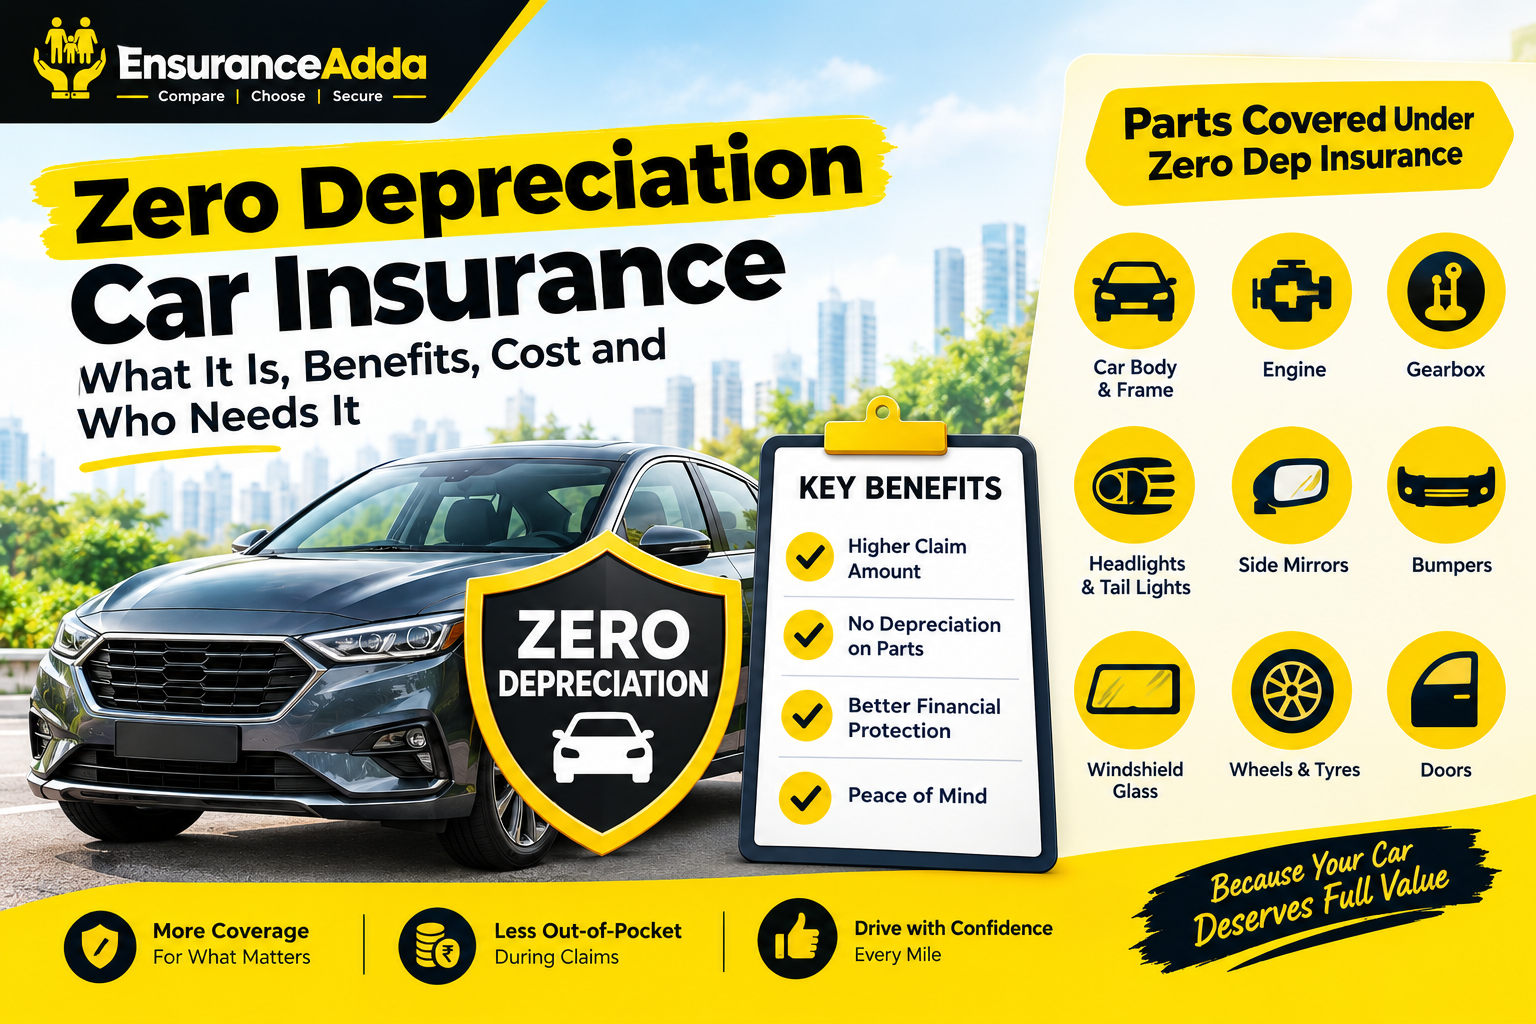
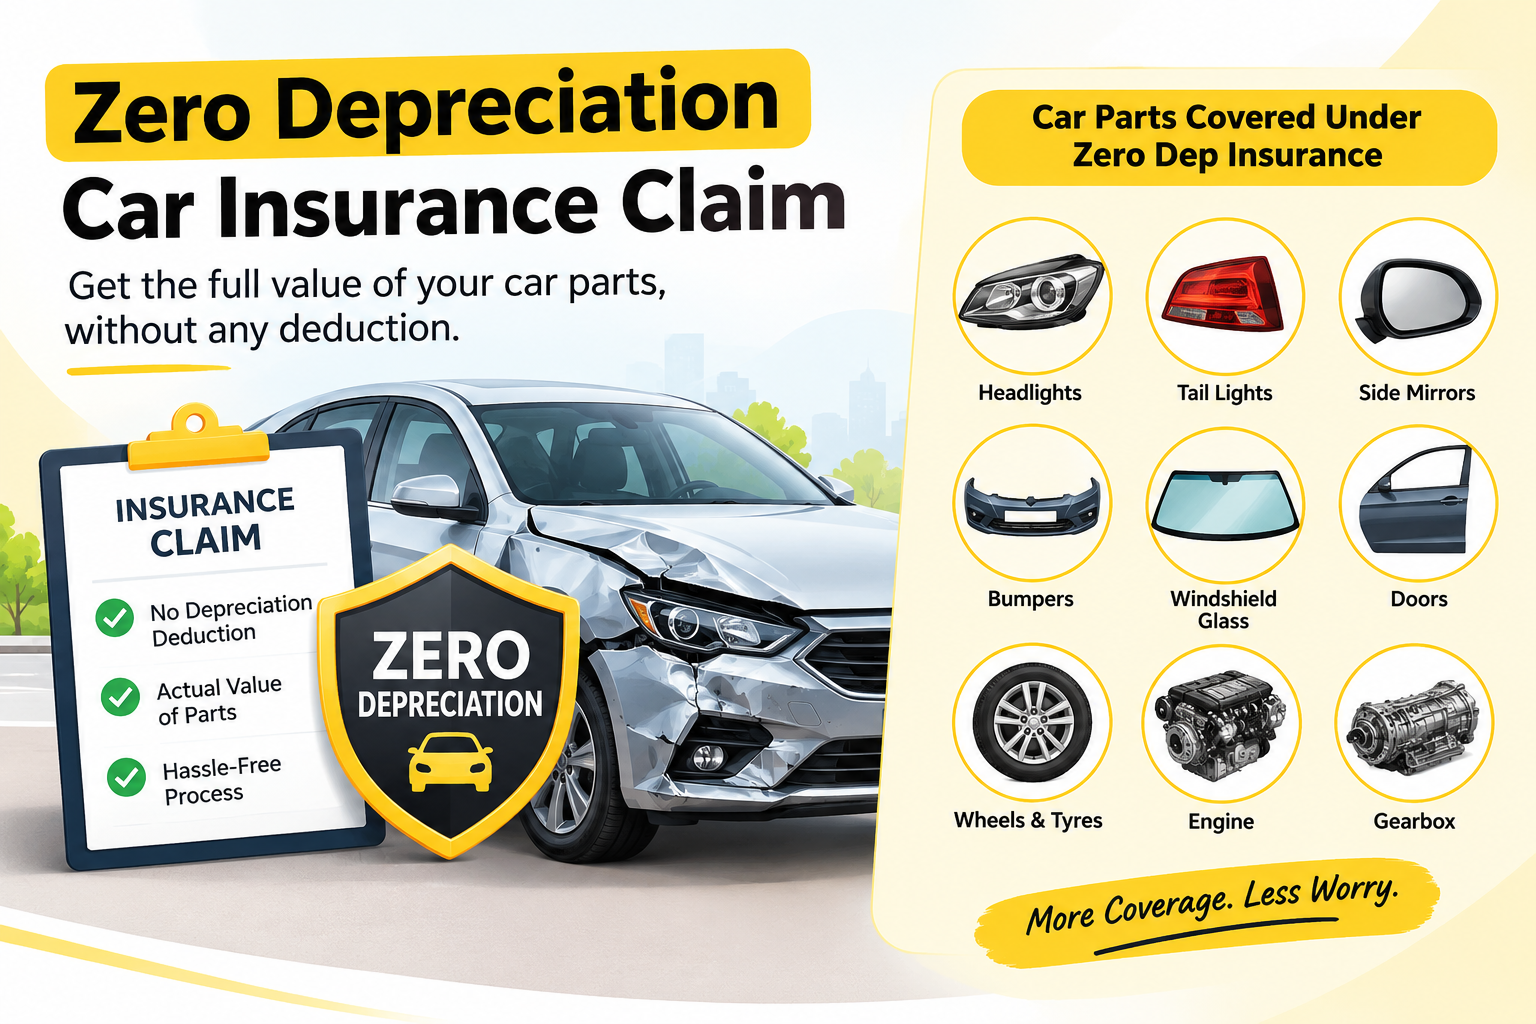
Zero depreciation car insurance is an add-on to your comprehensive car insurance policy. It is also called zero dep cover or bumper to bumper insurance. When you make a claim, the insurer pays the full cost of replaced parts without deducting depreciation.
In a standard comprehensive policy, the insurer deducts depreciation on parts like plastic, rubber, fibre and glass. That deduction means you pay part of the repair cost from your own pocket. With zero depreciation cover, that deduction is removed on eligible parts, so you pay much less (usually just the deductible and a few non-covered items).
How Does Depreciation Work in Car Insurance?
Every car part loses value with age and use. Insurers apply standard depreciation rates when settling claims on replaced parts. As a general guide, the rates look like this:
| Part type | Typical depreciation |
|---|---|
| Rubber, nylon, plastic parts and batteries | Around 50% |
| Fibreglass components | Around 30% |
| Metal parts (depends on car age) | Increases with age of the vehicle |
| Glass | Usually no depreciation |
Exact rates vary by insurer and policy, so always check your policy wording.
Example: Suppose a replaced plastic bumper costs ₹10,000. With a standard policy and 50% depreciation, the insurer pays about ₹5,000 and you pay the rest. With zero depreciation car insurance, the insurer pays the full ₹10,000 (minus your deductible, if any).
Key Benefits of Zero Depreciation Car Insurance
1. Higher Claim Amount
You get the full value of replaced parts, so the claim settlement is much closer to the actual repair bill.
2. Lower Out-of-Pocket Expenses
Repairs on modern cars are expensive. Sensors, headlights, bumpers and body panels cost a lot. Zero dep cover reduces what you pay from your own savings.
3. Peace of Mind
You don’t need to calculate depreciation or worry about surprise deductions at claim time.
4. Ideal for New and Premium Cars
New cars lose value quickly, and spare parts for premium models are costly. This add-on protects your investment during the years you need it most.
5. Better Value on Minor Accidents
Even small dents and scratches can involve costly part replacement. Zero dep cover makes these claims far more worthwhile.
What Does Zero Depreciation Cover Include?
Zero depreciation car insurance typically covers:
- Plastic, rubber and fibre parts
- Bumpers, headlights and body panels
- Metal parts affected in an accident
- Paint and labour costs on covered repairs (as per policy terms)
What Is Not Covered?
No add-on covers everything. Zero depreciation cover usually excludes:
- Normal wear and tear
- Mechanical or electrical breakdowns
- Engine damage from water ingress, unless you’ve bought an engine protection add-on
- Tyres and batteries (often partly or fully excluded)
- Consumables like nuts, bolts, oil and coolant, unless a consumables add-on is included
- Damage caused by drunk driving or driving without a valid licence
- Losses not covered by the base comprehensive policy
Always read the policy document before buying.
Zero Depreciation Car Insurance Cost
The add-on usually raises your premium by roughly 15% to 20% over a standard comprehensive plan, though this varies by insurer. Factors that affect the cost include:
- Car age and model: Newer and premium cars cost more to cover.
- Insurance Declared Value (IDV): A higher IDV means a higher premium.
- City of registration: Metro cities usually see higher premiums.
- Claim history: Your No Claim Bonus (NCB) and previous claims matter.
- Insurer and plan type: Pricing differs across companies.
Although the premium is higher, the money you save on one or two claims often outweighs the extra cost.
Who Should Buy Zero Depreciation Car Insurance?
Zero depreciation car insurance is a smart choice if:
- You own a new car (typically up to 3 to 5 years old)
- You drive a premium or luxury vehicle with costly spare parts
- You drive in heavy city traffic, where minor accidents are common
- You are a new driver and more likely to have small mishaps
- You want maximum claim value and minimal out-of-pocket spending
It may be less useful if your car is more than 5 years old, as many insurers don’t offer the add-on for older vehicles.
Things to Check Before Buying
- Claim limit: Many insurers allow only a limited number of zero dep claims per policy year (commonly two).
- Car age eligibility: Some insurers restrict the add-on to cars under a certain age.
- Inclusions and exclusions: Compare what each plan covers, especially consumables, tyres and batteries.
- Claim settlement ratio: Choose an insurer known for smooth and timely settlements.
- Network garages: More cashless garages mean easier repairs.
- Premium vs benefits: Don’t pick the cheapest plan blindly. Compare value, not just price.
How to Buy or Add Zero Depreciation Cover
- Compare comprehensive car insurance plans online.
- Select the zero depreciation add-on while buying or renewing your policy.
- Review the premium, exclusions and claim conditions.
- Complete the payment and download your policy document.
Note that this add-on is normally offered only at purchase or renewal, not mid-term.
Zero Depreciation vs Standard Comprehensive Insurance
| Feature | Standard comprehensive | Zero depreciation |
|---|---|---|
| Depreciation deduction | Applied | Not applied on eligible parts |
| Claim payout | Lower | Higher |
| Premium | Lower | Higher (about 15 to 20% more) |
| Best for | Older cars | New and premium cars |
Frequently Asked Questions (FAQs)
Q1. What is zero depreciation car insurance?
It is an add-on to comprehensive car insurance that pays the full cost of replaced parts without deducting depreciation.
Q2. Is zero depreciation car insurance worth it?
Yes, for new or expensive cars and frequent city drivers, because it reduces out-of-pocket costs on claims.
Q3. Can I buy zero depreciation cover for an old car?
Most insurers offer it only for cars up to about 5 years old, though this varies. Check with your insurer.
Q4. How many claims can I make under zero dep cover?
Many policies limit it to two claims per year. Check your policy for the exact limit.
Q5. Does zero depreciation cover tyres and batteries?
Usually not fully. These are often excluded or covered only partially.
Q6. Does zero depreciation insurance affect my No Claim Bonus?
A claim can affect your NCB, so compare the claim value against the NCB you’d lose for small repairs.
Conclusion
Zero depreciation car insurance is one of the most useful add-ons you can choose, especially for newer and high-value cars. It cuts deductions, raises your claim payout and protects your savings from costly repairs. The extra premium is modest compared with the potential savings. Before you buy, compare plans, check exclusions and claim limits, and pick an insurer with a strong claim record.